Public Adjuster Manhattan NY
Republic Claims Associates is the public adjuster Manhattan NY property owners call when a fire, water loss, or other property damage claim is on the line. A public adjuster works for you, the policyholder, while your insurer’s own adjuster works for the company that’s paying the claim, and that difference shows up directly in what you recover.
Republic Claims Associates, also known as Adjusters On Call, has represented property owners across the New York metro area since 1989. Founder Frank Rivela holds the Senior Professional Public Adjuster designation, ranking him in the top 1% of adjusters nationally, and brings 43 years of personal insurance industry experience to every Manhattan claim we take on. Over nearly four decades, the firm has handled more than $1 billion in claims.
We handle homes, businesses, and commercial property throughout Manhattan. Fire, water, wind, smoke, vandalism, burglary, if it’s a first-party property claim, it’s what we do. We don’t handle auto claims, and we never will. That focus is deliberate.
Why Hire a Public Adjuster Before Calling Your Insurer?
Insurance companies are profitable partly because claims get underpaid. Not always through bad faith. Sometimes it’s an adjuster working dozens of files at once who misses hidden damage, or a settlement calculated on outdated repair costs. In a market as dense and high-value as Manhattan, that gap between what’s offered and what’s owed can be substantial.
The National Association of Public Insurance Adjusters has documented for decades that policyholders represented by a licensed public adjuster tend to recover measurably higher settlements than those who negotiate directly with their carrier. We’re accredited members of NAPIA, which means we’re held to the organization’s ethics code and continuing education standards, not just a state license renewed once and forgotten.
What Makes Manhattan Public Adjustment Different?
Manhattan’s building stock creates claim issues that don’t come up the same way in other boroughs, and we work all of it: co-op and condo buildings, pre-war walk-ups, high-rise commercial towers, and ground-floor retail alike.
- Co-op and condo master policies versus individual unit owner coverage, and where the line between them actually falls
- Building department violations and landmark or historic district requirements that complicate repairs after a loss
- High-density multi-tenant buildings where one claim affects several units or businesses at once
- Commercial leases with tenant improvement and betterment coverage that owners and tenants alike often miss
Manhattan public adjustment isn’t the same exercise as a single-family home claim in a lower-density market, and treating it that way is how claims get underpaid.
What Changes When You Bring Us In First
- We review your policy line by line, including riders and endorsements most owners never read
- We document every category of loss, not just the obvious ones, before repairs or demolition erase the evidence
- We prepare the proof of loss and building estimate ourselves, rather than accepting your carrier’s number as the starting point
- We negotiate directly with the insurance company, so you’re not on the phone defending your own damage to someone paid to minimize it
- We track every deadline in the claims process, since a missed proof-of-loss window can cost you the entire claim
What Property Claims Do We Handle in Manhattan?
Fire and Smoke Damage Adjustment
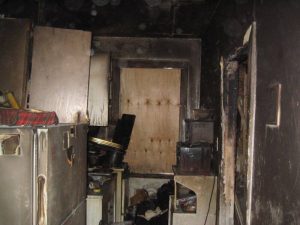
Fire damage public adjustment covers building damage, smoke and soot infiltration into HVAC systems, contents loss, and code upgrade costs tied to rebuilding to current standards. A fire doesn’t just damage a structure. It displaces tenants, interrupts income, and in Manhattan’s dense buildings, often affects more than just the unit where it started.
Water Damage Adjustment
Water damage public adjustment covers burst pipes, appliance failures, and the kind of multi-unit water intrusion common in Manhattan’s older co-op and condo buildings, where one failure upstream can cascade through several units below. Getting the timeline and cause documented correctly often decides whether a carrier treats the loss as sudden and covered or gradual and disputed.
Vandalism and Burglary Adjustment
Vandalism and burglary claims cover break-in damage and intentional property destruction that carriers frequently undervalue, especially when a police report is treated as the whole claim instead of a starting point.
Commercial Fire and Water Damage Adjustment
Commercial fire and water damage adjustment, covered further down this page under large loss claims, carries a component most owners miss: business income, the revenue a business would have earned had the loss not happened, often the single largest piece of a commercial claim and the one carriers dispute hardest. We also handle tenant improvements and betterments, the buildout a commercial tenant invested in, millwork, fixtures, custom finishes, which is often covered under the tenant’s own policy even though the landlord owns the building, along with the landlord-tenant coverage splits common in Manhattan’s leased commercial space.
Co-op and Condo Claim Adjustment
Co-op and condo public adjustment covers master-policy-versus-unit-owner disputes, upstream water failures that cascade through several units, and board-versus-owner coverage questions that come up constantly in Manhattan’s co-op and condo stock.
Wind and Storm Damage Adjustment
Wind and storm damage adjustment covers roof and facade damage on Manhattan’s older building stock, along with the water intrusion that typically follows. We handle this as part of the fire and water damage work above, since the damage almost always traces back to one or the other.
When Does a Manhattan Claim Become a Large Loss?
Most public adjusters and carriers treat claims above roughly $250,000 as large loss, though no single figure is written into every policy. Manhattan’s property values and rebuild costs push claims into that range faster than almost anywhere else: a mid-size commercial fire, a multi-floor co-op water loss, or a building-wide storm claim can all cross the threshold quickly. A few factors push a claim into large-loss territory beyond the raw damage number:
- Business interruption or loss of rents that extends the financial impact months past the physical repair
- Multiple coverage components, building, contents, code upgrade, and extra expense, each requiring separate documentation and negotiation
- A carrier assigning its own large-loss specialist, and sometimes an outside engineering firm, to dispute causation or scope
- Code compliance and landmark or historic district requirements common once a Manhattan building is opened up for repair
At that scale, your insurer doesn’t send one adjuster. It sends a team, often including an engineer, a forensic accountant, and coverage counsel. Our in-house attorneys, accountants, and real estate broker mean a disputed clause, a business-interruption number, or a tenant relocation issue doesn’t wait on an outside vendor’s schedule the way it would with a firm that subcontracts that work out.
How Does Republic Claims Associates Compare to Other Manhattan Public Adjusters?
Most public adjusting firms in the Manhattan market subcontract anything outside straight property damage, which adds weeks to a claim every time it needs legal, financial, or real estate input. Republic Claims Associates is structured differently in a few specific, verifiable ways:
- Founded in 1989, with Frank Rivela personally holding the Senior Professional Public Adjuster designation, a top-1%-of-the-field credential
- Attorneys, accountants, and a real estate broker on premises, so business income, coverage disputes, and relocation don’t wait on an outside vendor’s schedule
- More than $1 billion in career claims recovered, with NAPIA accreditation and licenses active across nine jurisdictions
That in-house structure matters most on the claims that aren’t just about the building. A commercial tenant has a business income component. A co-op unit owner has a master-policy-versus-individual-policy question to untangle. Our in-house accountants and staff build those numbers and that analysis directly, rather than waiting on a subcontractor’s schedule, the way a firm without that staff on payroll has to.
Founded in 1989, Republic Claims Associates has represented property owners since well before most of today’s Manhattan public adjusting firms existed, and is now licensed across nine jurisdictions with affiliate catastrophe coverage nationwide.
How Does New York’s Fee Cap Protect You?
New York State caps public adjuster compensation at 12.5 percent of the claim recovery. We work on contingency, meaning you pay nothing upfront and nothing at all unless we recover money for you. The percentage we charge is disclosed in writing before you sign anything, and it typically runs lower on larger claims than smaller ones.
Frequently Asked Questions
Does hiring a public adjuster in Manhattan cost anything upfront? No. We work on contingency, and New York law caps the fee at 12.5 percent of whatever we recover. You pay nothing if we don’t get you a settlement.
Do you handle co-op and condo claims in Manhattan? Yes. We work directly with boards, managing agents, and individual unit owners to sort out what the master policy covers versus what falls to an individual owner’s policy, which is one of the most commonly contested issues in Manhattan multi-unit claims.
Can I still hire a public adjuster after I’ve already filed my claim? Yes, though the earlier we’re involved, the more evidence is still intact. If your carrier has already made a low offer, we can review it and reopen negotiations.
Do you handle claims for Manhattan businesses as well as homeowners? Yes. We represent homeowners, co-op and condo owners and boards, landlords, and business owners across Manhattan. Auto claims are the only property type we don’t handle.
What’s the difference between a public adjuster and my insurance company’s adjuster? Your insurer’s adjuster works for the insurance company and is paid whether your claim is high or low. A public adjuster is licensed under New York Insurance Law to represent you, the policyholder, exclusively.
How much does a loss have to be before it needs large-loss handling? Most large-loss public adjusters, including our team, treat claims above roughly $250,000 as requiring specialized handling, with in-house accountants, attorneys, and engineering support brought in from day one. Below that, a general residential or commercial claim is usually sufficient.
Republic Claims Associates has handled property claims across the New York metro area for more than three decades. If you’ve had fire, water, vandalism, or other property damage in Manhattan, call us at (718) 356-7000 for a free claim review, or request a free consultation online.


