A water damage public adjuster Long Island homeowners trust documents a loss before repairs and drying cover up how far the water actually traveled, and Republic Claims Associates is that water damage public adjuster Long Island turns to for exactly that. A burst pipe, roof leak, or coastal storm rarely stays contained to one area. Water moves through framing, flooring, and wall cavities into rooms and systems the original source never touched, and the claim has to capture all of it.
Republic Claims Associates represents the property owner in valuing that damage correctly. We document everywhere the water reached, not just the visible source, and negotiate the settlement so your carrier isn’t the only one setting the scope of the claim.
What Causes Water Damage Claims on Long Island?
Coastal storms and nor’easters. Long Island’s coastline and bays mean storm-driven water intrusion is a regular part of property claims here, and sorting out wind damage from flood damage often decides which coverage actually applies.
Burst and frozen pipes. Common across Nassau and Suffolk Counties’ older housing stock, especially
during winter cold snaps when unheated spaces freeze.
Roof leaks. A frequent source of claims, particularly on older roofing systems where failure develops gradually and is sometimes disputed by carriers as a maintenance issue rather than a sudden loss.
Appliance and fixture failures. Washing machine hose failures, dishwasher leaks, and water heater ruptures, often found only after damage has already spread.
Sewer and drain backup. Backups from building or municipal lines, which carry contamination risk beyond the water damage itself and require different handling under most policies.
Why Do Wind-Versus-Flood Disputes Happen After a Storm?
After a coastal storm, insurance carriers draw a hard line between wind damage, which a standard property policy typically covers, and flood damage, which usually requires separate NFIP or private flood coverage. When a storm brings both wind and water at once, a carrier’s first move is often to attribute as much of the damage as possible to flood, since that shifts responsibility to a different policy or a different carrier entirely.
Getting the cause and timeline documented correctly from the first inspection matters more on a Long Island water claim than almost any other property loss, since that documentation often determines whether a claim is accepted at full value, reduced, or denied outright.
Is the Damage You Can See the Whole Claim?
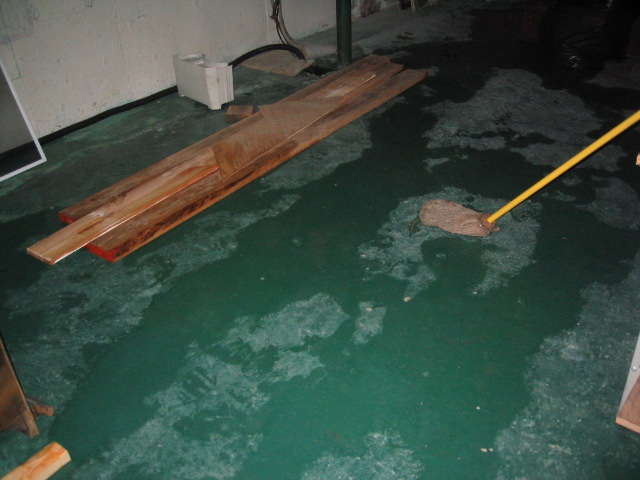
Rarely. Water travels along framing and through wall cavities, and mold can begin developing within 24 to 48 hours in areas that stay wet longest. A carrier’s initial inspection sometimes misses this, particularly if repairs or drying began before a thorough inspection happened.
- Moisture behind drywall and baseboards that isn’t visible without moisture meters or thermal imaging
- Subfloor and structural framing damage that requires opening up finished surfaces to assess
- HVAC and ductwork contamination if the water reached mechanical systems
- Mold growth in areas that stayed wet during the delay between the loss and full remediation
How Do We Handle a Long Island Water or Storm Damage Claim?
- Immediate documentation. We inspect the property as quickly as possible after a loss, before emergency mitigation or repairs remove evidence of the full extent of damage.
- Cause determination. We document the timeline and cause clearly, which matters directly for whether a carrier treats the loss as wind, flood, or a covered sudden event.
- Full-scope assessment. We check for hidden moisture and structural damage beyond what’s immediately visible.
- Policy review. We read the full policy, and any separate flood policy, to identify exactly what each one covers and where responsibility falls when both are involved.
- Negotiation. We handle every conversation with the insurance company through to final settlement.
Why Choose Republic Claims for a Long Island Water Damage Claim?
Wind-versus-flood disputes come down to credibility, and credibility comes from track record. Founder Frank Rivela has 43 years in the insurance industry behind him and holds the Senior Professional Public Adjuster designation, a top-1%-of-the-field credential. Since founding the firm in 1989, Republic Claims Associates has recovered more than $1 billion for policyholders, maintains accreditation with the National Association of Public Insurance Adjusters, and operates a Hampton Bays office serving Nassau and Suffolk Counties directly.
A water or storm loss involving extensive structural damage, a multi-unit property, or significant business interruption may qualify as a large loss claim, and our in-house accountants and attorneys handle that complexity without bringing in outside vendors mid-claim. If a burst or frozen pipe is the specific cause of your loss, our burst pipe insurance claim page covers that sudden-versus-gradual distinction in more depth.
How Does Republic Claims Associates Compare on Water Damage Claims?
- Moisture meters and thermal imaging used as standard practice, not just a check of visibly damaged surfaces
- Wind-versus-flood causation documented from the first inspection, before a carrier can shift responsibility between policies
- $1 billion+ in career claims recovered across 43 years of founder experience, representing property claims exclusively
How Does New York’s Fee Cap Protect You?
Under New York law, we’re required to disclose our fee percentage in writing before starting work. The arrangement is strictly contingency, meaning no cost to you unless we recover a settlement.
Frequently Asked Questions
Does homeowners insurance cover burst pipe damage on Long Island? Generally yes, since a burst pipe is typically treated as sudden and accidental damage. Gradual leaks that developed over time are more likely to be disputed or excluded, depending on your policy.
Is flood damage covered under a standard homeowners or commercial policy? Usually not. Flood damage typically requires separate flood insurance, often through the National Flood Insurance Program, while water damage from an internal source like a burst pipe is covered under a standard property policy.
How is wind damage different from flood damage after a coastal storm? Wind damage, including rain that enters through wind-caused openings, is typically covered under a standard property policy. Flood damage from rising water is usually excluded and requires separate flood coverage. The two often happen in the same storm, which is exactly why the distinction gets disputed.
Does my policy cover mold that develops after a water loss? Many policies cover mold that results directly from a covered water loss, though coverage limits and exclusions vary significantly.
How quickly should I document water or storm damage after discovering it? As soon as possible. Delayed documentation makes it harder to establish the timeline and cause, which affects whether the carrier treats the loss as covered wind damage, excluded flood damage, or something in between.
If your Long Island property has water, storm, or flood damage, documenting the full extent early protects your claim. Call us at (800) 246-4417 for a free claim review, or request a free consultation online.


